Palau presents a niche opportunity within the Pacific region for online gaming operators seeking to expand into regulated environments. The country’s regulatory landscape remains minimally developed, offering potential for strategic market entry but also posing compliance challenges. Understanding Palau’s legal environment is essential for assessing market viability and operational risks.
| Metric | Value |
|---|---|
| Legal Status of Gambling | Limited regulation, advisory framework |
| Population | 18,200 (2025 estimate) |
| GDP | ~$300 million |
| Internet Penetration | ~75% |
| Mobile Penetration | ~95% |
| License Cost | $50,000 – $100,000 |
| Tax Rate on GGR | Not explicitly defined, proposed 10-15% |
| Market Entry Timeline | 6-12 months |
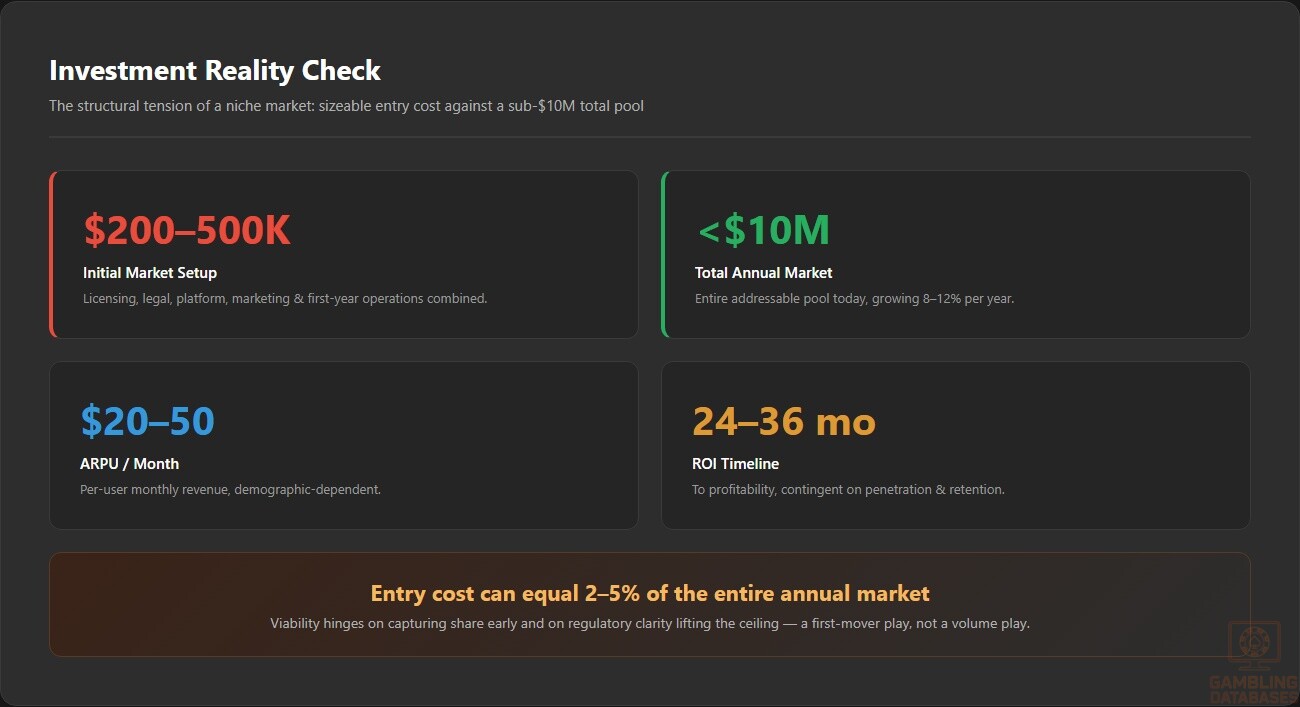
| Market Size | Emerging, <$10 million annually |
| Regulatory Barriers | Minimal formal licensing, high due diligence demand |
| Growth Forecast (CAGR) | 8-12% over next 5 years |
| Average Revenue Per User (ARPU) | $20 – $50/month |
| Market Penetration | Low but Growing |
Regulatory Framework and Legal Environment
Current Gambling Regulation Status
Palau’s gambling landscape is characterized by an informal, largely unregulated environment. The government has issued advisory guidelines rather than comprehensive legislation, which creates a hybrid atmosphere for online gaming operators. Virtual gambling activities are mainly conducted through offshore licenses, with the local authorities adopting a cautious, non-interventionist stance.
Land-Based Gambling Activities
Palau hosts a limited number of land-based gambling venues, primarily in the form of small casinos and slot machine halls operated under special permits. These venues are tightly regulated, focusing chiefly on social and tribal gaming. Sports betting conducted in physical outlets remains illegal, with enforcement concentrated on unlicensed activities.
Online Gambling Framework
Digital gaming regulation in Palau remains an evolving area. The government has yet to establish a formal licensing regime but has indicated a move toward regulatory clarity to attract offshore operators. Currently, online betting sites are mostly offshore entities operating under licenses from jurisdictions with established frameworks, such as Curacao or the Philippines. Palau does not have explicit laws prohibiting or endorsing online gambling, creating a gray zone for operators.
Licensed Operators and Market Players
The market is predominantly occupied by offshore licensees, with no local licenses issued to date. Few operators openly target Palau residents, and the market size is mainly driven by international players seeking jurisdictional advantages. As local regulatory oversight is limited, market entry strategies often rely on offshore licensing and regional marketing efforts.
Licensing Framework and Requirements
Palau’s licensing process is informal, involving approval from the Palau Gaming Commission or related authorities. To apply, operators must demonstrate financial stability, technical competence, and compliance with international standards. Application fees are typically estimated at $50,000 to $100,000, with a process duration of 6 to 12 months, depending on completeness and due diligence results.
Local Presence and Operational Requirements
Foreign operators are not mandated to establish physical offices in Palau but must ensure their online platform complies with local standards. There are no strict domain registration requirements, though local branding might be beneficial for market penetration. No minimum staffing levels are specified, but compliance with AML and responsible gambling policies is expected.
Compliance Obligations and Monitoring
Palau emphasizes anti-money laundering (AML) and know-your-customer (KYC) procedures, requiring operators to verify players’ identities thoroughly. Responsible gambling measures include self-exclusion options and informational disclosures, although formal enforcement policies are underdeveloped. Ongoing monitoring involves periodic audits and transparent reporting of suspicious activities.
Financial Monitoring and Reporting
- Implement transaction monitoring systems aligned with international standards
- Conduct regular audits of financial transactions
- Report suspicious activity to authorities in accordance with AML policies
- Maintain detailed records for at least five years
Player Taxation
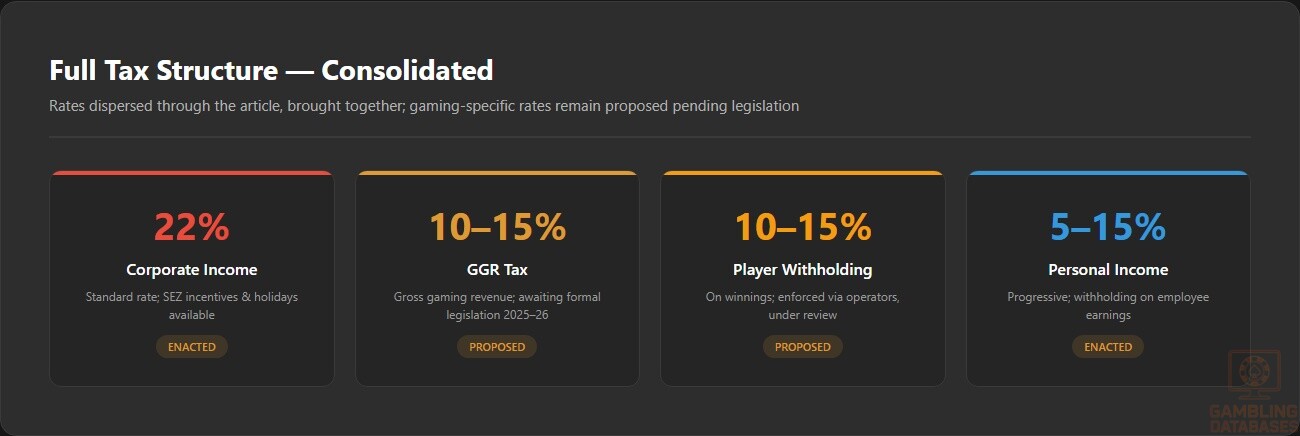
Palau has yet to establish formal taxation on player winnings. Preliminary discussions suggest a potential withholding tax of around 10-15% on gross winnings, to be enforced via offshore operators.
Operator Taxation
Operators may face a proposed gross gaming revenue tax rate of 10-15%. Additional operational taxes and license renewal fees are expected to be introduced once formal legislation is enacted. These figures are subject to legislative approval, with formal rates anticipated within 2025-2026.
Gambling Market Financial Performance
The overall market remains small, with annual betting volume estimated below $10 million. Growth is driven mainly by offshore operators serving regional players. Revenue trends indicate steady increases of approximately 8-12% per year, expected to accelerate as regulatory clarity improves.
Advertising and Marketing Restrictions
Palau enforces limited regulation on marketing, focusing on responsible advertising. Operators are advised to avoid aggressive promotional practices, with restrictions on misleading content and age-specific marketing. Sponsorships and advertisements must comply with general advertising standards that promote responsible gambling.
Recent Regulatory Changes and Their Impact
Pending legislation in 2024 proposed formal regulation and licensing reforms, aiming to create a transparent, controlled environment. These changes are expected to increase licensing costs slightly but will improve market credibility and attract reputable operators. The shift may also lead to higher compliance standards and operational costs.
Enforcement Mechanisms and Penalties
Enforcement remains limited but is expected to strengthen with new legislation. Penalties for illegal gambling activities include fines, license revocation, and potential criminal charges. The government plans to enhance monitoring capacity, focusing on offshore and domestic violations to safeguard regulatory integrity.
Section 2: Demographics and Consumer Analysis
Population Demographics and Distribution
Palau’s total population is approximately 18,200 as of 2025, with a youthful median age near 31 years. Gender distribution is fairly balanced, with a slight female majority at 51%. The age structure reveals a predominantly working-age population, offering a potential consumer base for iGaming, though the small population limits market scale.
Urbanization is moderate, with around 70% of residents living in urbanized areas primarily centered on key islands. Rural and outer island populations maintain traditional livelihoods, which affects digital adoption rates. Internet access and gambling venue concentration tend to cluster around main urban centers, especially Koror.
| Age Group | Percentage of Population |
|---|---|
| 0-14 years | 27% |
| 15-24 years | 18% |
| 25-54 years | 40% |
| 55-64 years | 8% |
| 65 years and over | 7% |
Geographic Distribution
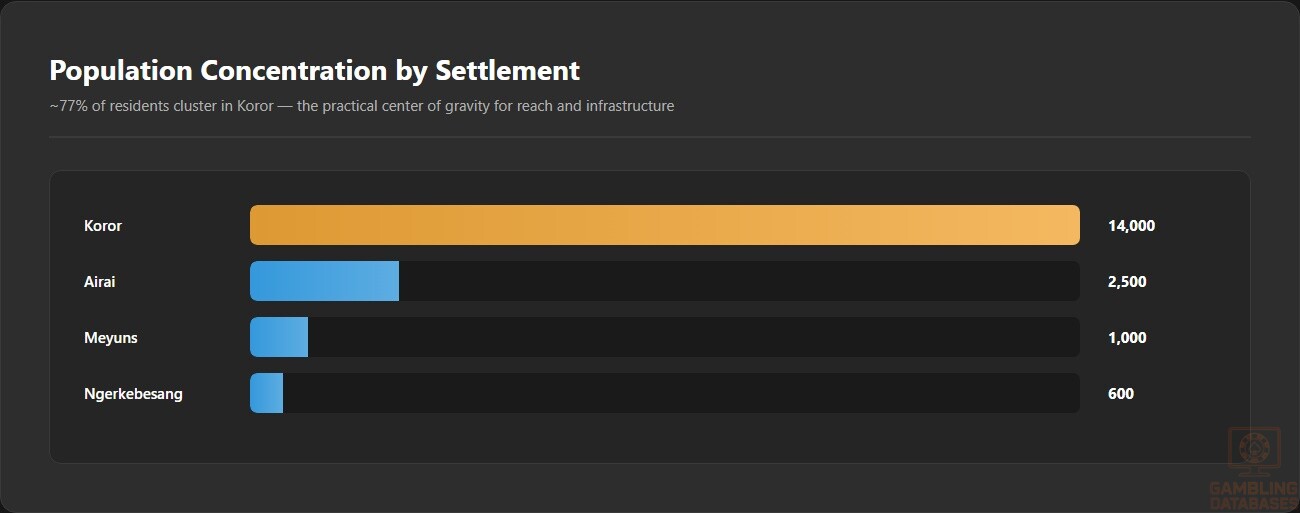
Palau’s population is dispersed across several islands, with the most significant urban center being Koror, the commercial hub. Other notable settlements include Airai and Meyuns, smaller in scale but regionally important. These areas host the majority of casinos and gambling-related services.
Internet infrastructure is concentrated on these populated islands, with broadband availability supporting digital connectivity. Gambling venues and service providers are equally focused here, reflecting both economic activity and consumer accessibility.
- Koror: Approx. 14,000 inhabitants
- Airai: Approx. 2,500 inhabitants
- Meyuns: Approx. 1,000 inhabitants
- Ngerkebesang Island: Approx. 600 inhabitants
- Others (outer islands): Sparse populations
Economic Indicators and Consumer Spending Power
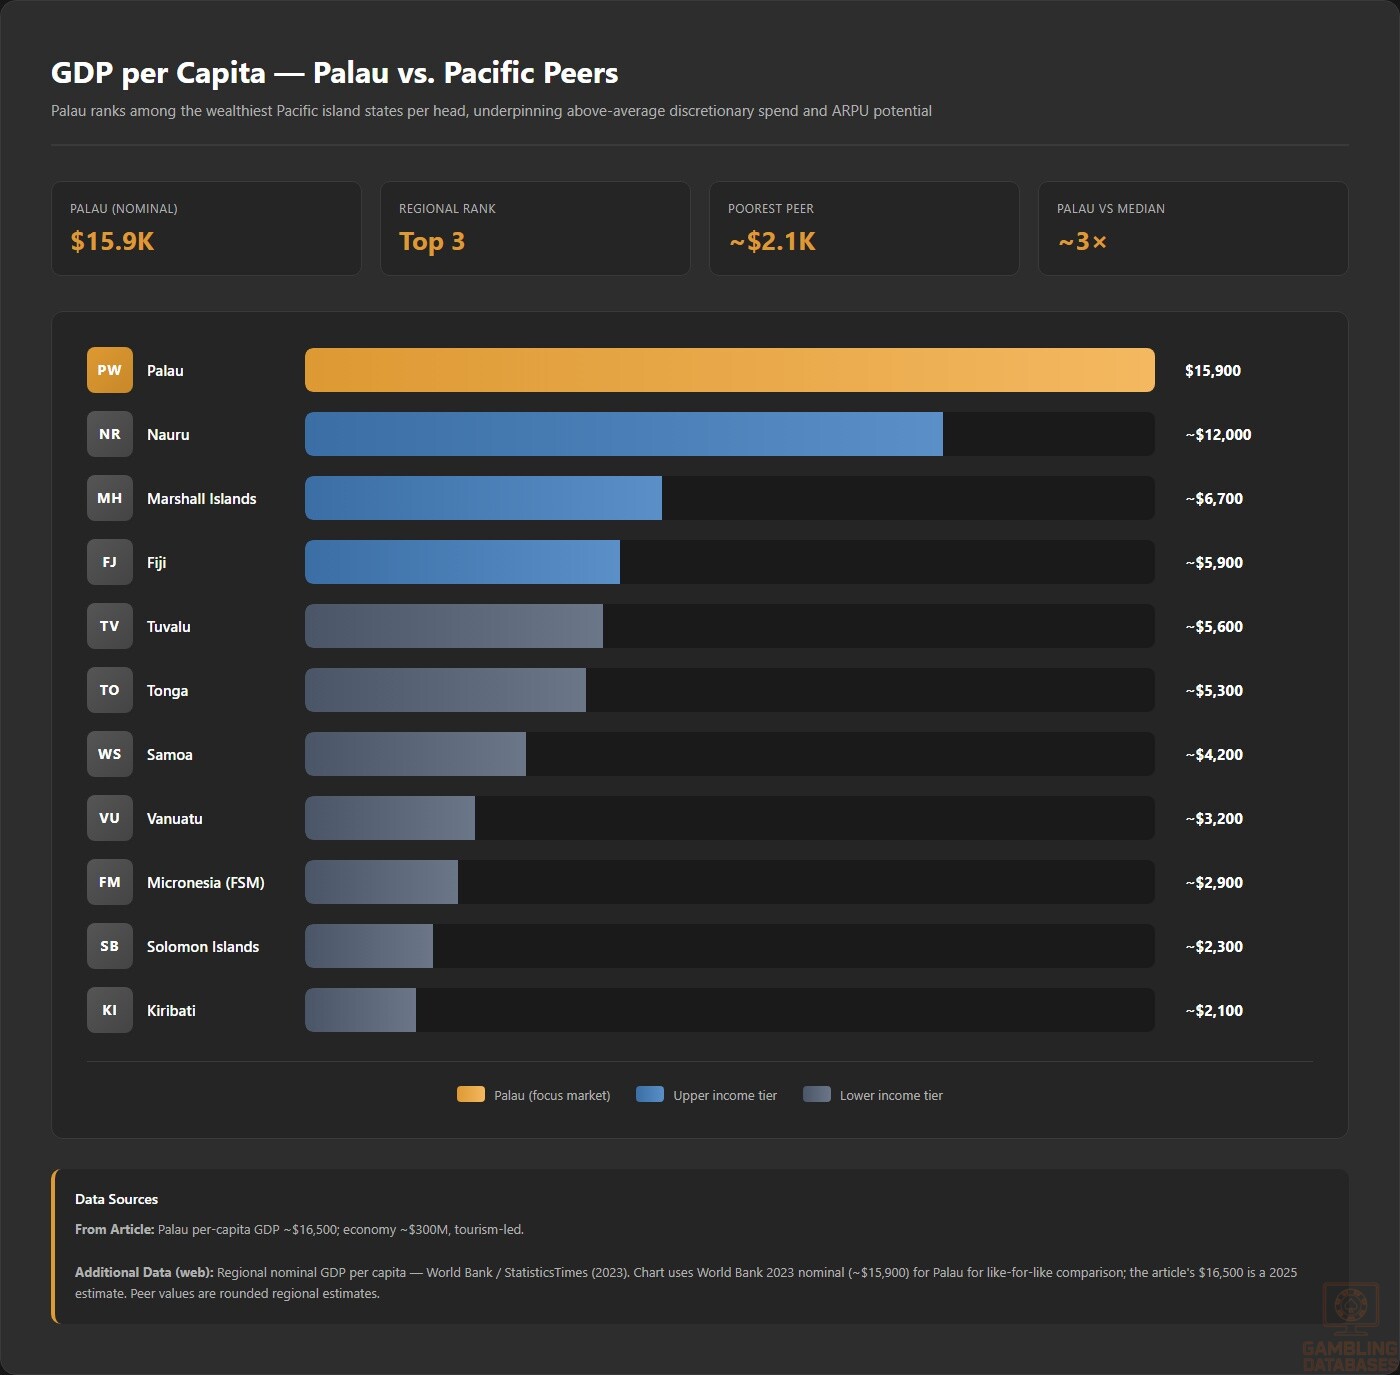
Palau’s GDP stands at about $300 million, reflecting a small island economy with tourism as the dominant sector. The economy shows steady growth forecasts of 3-5% annually, driven by tourism recovery and diversification efforts. Per capita GDP is approximately $16,500, indicating modest consumer spending capacity.
The economy is largely service-based, anchored by tourism, public administration, and retail sectors. This composition shapes consumer spending patterns, with discretionary income concentrated in urban areas where tourism-related employment prevails.
Income distribution evidences moderate inequality, with average household income around $20,000 annually but significant disparities among remote communities. Disposable income levels vary widely, influencing the affordability and accessibility of iGaming services.
| Indicator | Value |
|---|---|
| GDP | $300 million |
| GDP Growth Forecast | 3.5% CAGR |
| Per Capita GDP | $16,500 |
| Average Household Income | $20,000 annually |
| Service Sector Contribution | 72% of GDP |
| Industry Sector Contribution | 18% of GDP |
| Agriculture Sector Contribution | 10% of GDP |
Market Size and Growth Projections
The estimated iGaming market size remains small but growing, with annual revenues under $10 million. Historical data indicates gradual market development supported by increasing digital adoption. Forecasts project an annual growth rate between 8-12%, reflecting rising consumer interest and improved regulatory certainty.
Market penetration is currently low, less than 5%, but expanding as internet and mobile access improve. The Average Revenue Per User (ARPU) ranges from $20 to $50 monthly, contingent on user demographics and gambling activity types.
| Metric | 2023 | 2025 | 2030 (Projected) |
|---|---|---|---|
| Market Size (Revenue, $ million) | 6.5 | 9.2 | 15.8 |
| User Base (Thousands) | 1.1 | 1.8 | 3.4 |
| ARPU ($/Month) | 22 | 28 | 35 |
| Market Penetration (%) | 3% | 5% | 9% |
Education, Skills, and Digital Literacy
Palau exhibits a literacy rate exceeding 95%, with the majority of the population completing secondary education. Digital literacy levels vary, higher in urban centers where technology access is widespread. The workforce possesses foundational IT skills, supporting engagement with online services including iGaming platforms.
Continuous efforts in education policy aim to boost technical competencies, preparing the population for a digital economy. These skills enhance the consumer base’s capacity to participate confidently in regulated online gambling ecosystems.
Cultural and Social Factors
Communication and Language
Palauan and English are the official languages, with English predominating in business and digital communications. Other local dialects exist but have limited use in commerce and online interaction. English proficiency supports access to international iGaming platforms and content.
- Palauan
- English
- Sonsorolese
- Japanese (minority usage)
- Other Micronesian dialects
Cultural Attitudes
Gambling culturally holds mixed perceptions in Palau. While traditional gaming enjoys social acceptance in localized contexts, formal gambling activities face cautious scrutiny rooted in religious and community values. Foreign gambling brands are viewed pragmatically, with openness to reputable operators that adhere to ethical standards.
Entertainment preferences skew toward social and family-oriented activities, but increasing digital exposure is fostering gradual acceptance of iGaming as a leisure pursuit.
Problem Gambling and Social Considerations
Prevalence of problem gambling remains relatively low but is underreported due to social stigma. At-risk groups include younger adults and frequent digital users. The government has begun exploring support initiatives, though formal programs are nascent.
- Public awareness campaigns in urban centers
- Support hotlines managed by healthcare providers
- Community outreach and education programs
- Voluntary self-exclusion schemes promoted by operators
- Collaboration with regional treatment centers
Political Structure and Governance
Palau operates as a presidential republic with a stable political climate favorable to foreign investment. Governance is characterized by transparent regulation development, though legislative speed remains moderate. The country maintains positive international relations, underpinning reliability for market entrants seeking long-term engagement.
Regulatory consistency is improving, with incremental reforms aligning Palau to global financial and digital standards, enhancing investor confidence in the iGaming sector.
Technology Adoption and Digital Behavior
Internet and Digital Usage
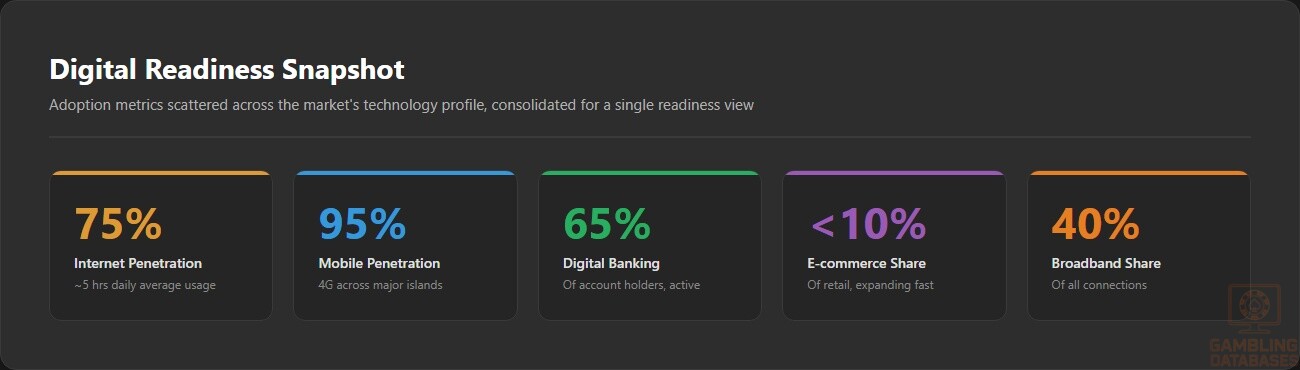
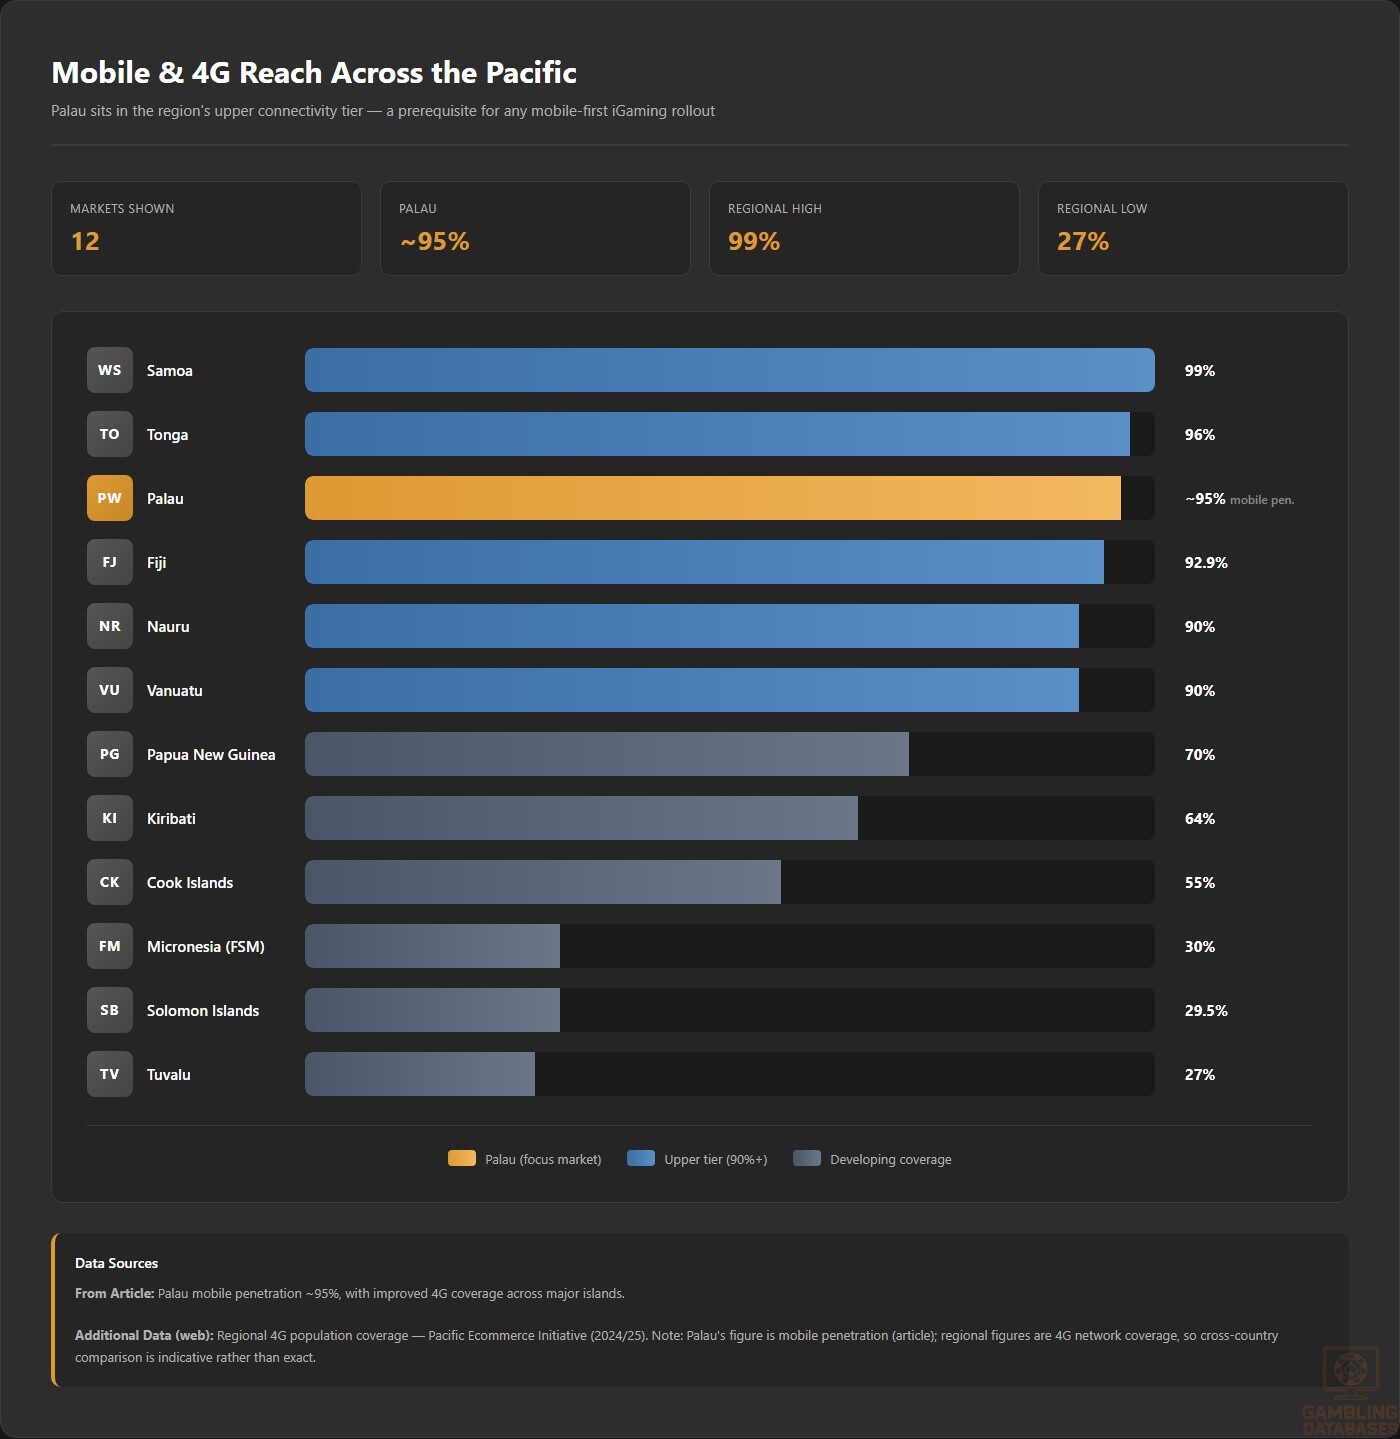
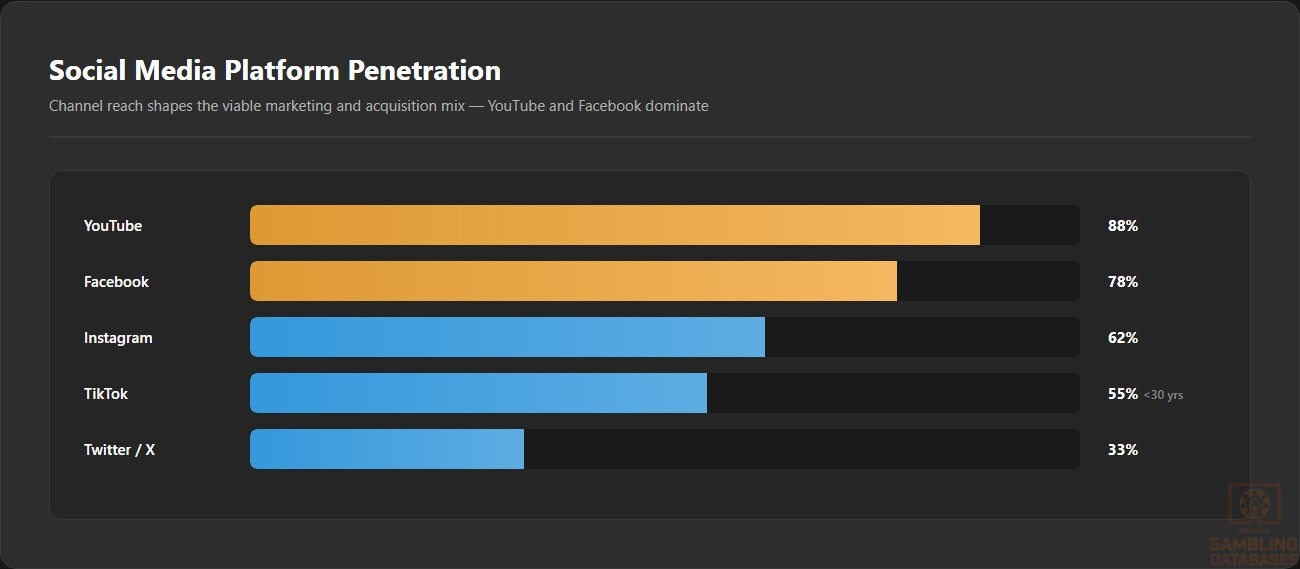
Internet penetration is approximately 75%, with daily usage averaging 5 hours. Mobile phone adoption is notably high at nearly 95%, driven by improved 4G coverage across major islands. Social media engagement is robust, reflecting regional trends toward digital communication and entertainment consumption.
- Facebook: 78% market penetration, primary platform for news and social connection
- Instagram: 62%, popular among young adults for visual content
- YouTube: 88%, dominant for video consumption
- TikTok: Rapid growth, 55% among users under 30
- Twitter: 33%, niche audience focused on news and events
Digital Payment Behavior
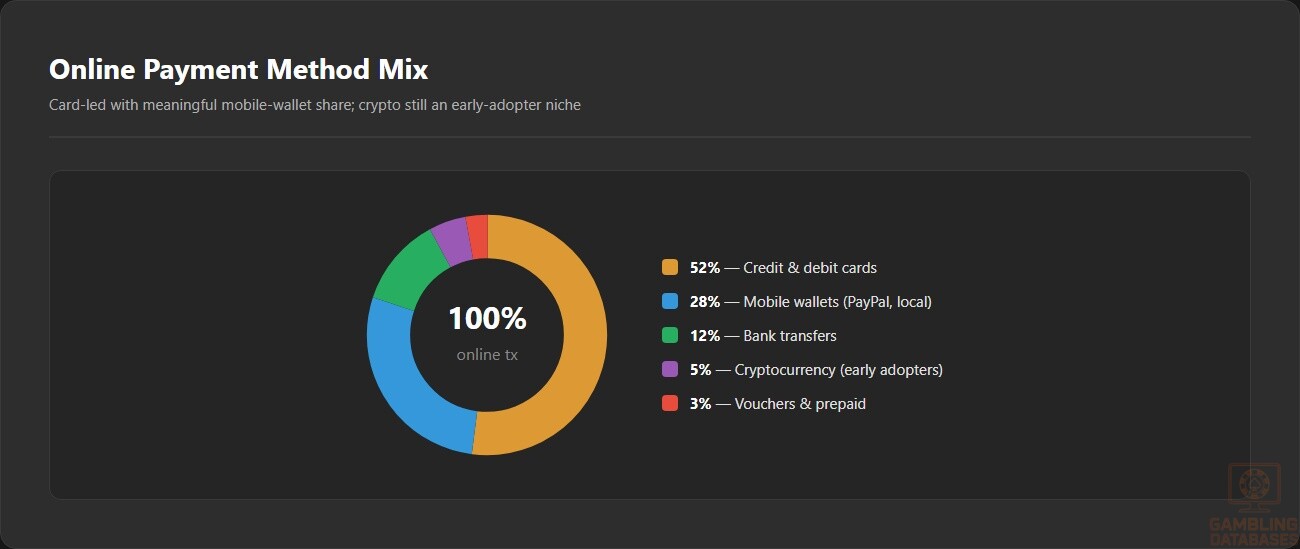
Online payment adoption is centered on bank cards and mobile wallets, with the market gradually embracing alternative digital methods. Cryptocurrency use remains limited but shows emerging interest from tech-savvy users. Preferences reflect regional payment landscapes influenced by tourism and remittance flows.
- Credit and debit cards: 52% of online transactions
- Mobile wallets (e.g., PayPal, local solutions): 28%
- Bank transfers: 12%
- Cryptocurrency payments: 5%, early adopters
- Cash-based vouchers and prepaid cards: 3%
Gaming and Gambling Preferences
Current Market Participation
Participation rates in gambling remain modest, with social card games and informal betting activities most prevalent. Online gambling adoption is in early stages but rapidly growing among urban youth. Lottery-type games and slots lead digital activity, followed by sports betting.
| Activity | Participation Rate |
|---|---|
| Social Card Games | 52% |
| Online Slots | 34% |
| Sports Betting | 28% |
| Lottery and Number Games | 24% |
| Casino Table Games | 18% |
Consumer Behavior Patterns
Users prefer mobile platforms for convenience, with peak gambling sessions occurring in evening hours. Average session length is approximately 30 minutes, with retention driven by promotional offers and engaging game designs. Spending is cautious but tends to increase with greater trust in regulatory oversight and platform fairness.
Retention strategies that emphasize responsible gambling support user longevity, while cross-platform accessibility enhances engagement across demographics.
Section 3: Technology Infrastructure and Business Environment
Internet and Digital Infrastructure
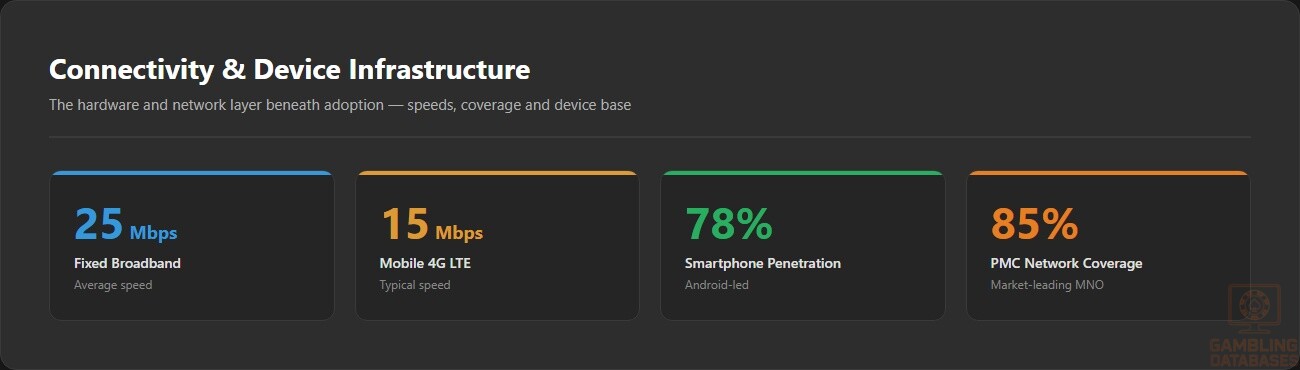
Palau’s internet penetration stands at approximately 75%, reflecting significant progress for a small island nation. Broadband access accounts for nearly 40% of connections, with the majority of users relying on mobile internet services. Average fixed broadband speeds hover around 25 Mbps, while mobile networks typically offer 15 Mbps on 4G LTE technology.
Network reliability is generally stable within urban centers, although remote islands experience intermittent connectivity due to geographic and infrastructure challenges. Investments in submarine cables and satellite links aim to enhance bandwidth and reduce latency.
5G and Future Technology Deployment
Palau is in the early stages of 5G deployment, with pilot programs initiated in Koror and Airai targeting government and commercial users. Nationwide 5G rollout is projected within 3-5 years, contingent on regulatory approval and infrastructure investments. The local telecom industry is primed to benefit from global technology partnerships, accelerating the digital ecosystem supporting iGaming and other online activities.
Mobile Technology Ecosystem
Palau has a competitive mobile network operator (MNO) landscape dominated by two primary providers. Market share distribution favors the incumbent operator, which covers 85% of the territory, while the smaller provider holds the remainder, focusing on urban hotspots. Data package costs are moderate, with prepaid plans dominating consumer uptake.
- Palau Mobile Communications (PMC): Market leader with comprehensive island-wide network
- Oceanic Telecom: Focuses on urban coverage and business clients
- Emerging MVNOs: Limited presence, targeting niche segments
- Satellite Internet Providers: Supplementary coverage for remote areas
- International Roaming Services: Supported by major global networks
Smartphone penetration is robust, estimated at 78%, with Android devices leading due to affordability and app availability. High-end iOS devices account for a smaller but growing segment, mainly among business professionals and younger urban users. Device usage patterns indicate strong engagement with mobile apps, social media, and online entertainment platforms.
Financial Services and Payment Infrastructure
The banking sector in Palau comprises several established commercial banks providing a broad range of retail and corporate services. Digital banking adoption has accelerated, with about 65% of bank account holders utilizing mobile or online platforms regularly. Account penetration is moderate, with rural populations facing access barriers.
- First Palau National Bank – Largest retail and corporate banking services
- Palau Community Bank – Focus on SME and community banking
- Pacific Islands Development Bank – Development and project financing
- Citibank Palau Branch – International banking and foreign exchange
- Island Commercial Bank – Local business and retail banking
- Digital-Only Banks – Emerging, focused on mobile-first services
Payment processing options include wide acceptance of credit/debit cards, mobile wallets, and bank transfers. E-wallet adoption is growing, supported by international providers and select local solutions adapted to island commerce. Cryptocurrency remains experimental, used primarily within fintech-savvy circles but lacking regulatory clarity.
- Visa and MasterCard: Widely accepted cards for online and offline payments
- PayPal: Popular digital wallet for cross-border transactions
- Local Mobile Wallets: Growing adoption among younger consumers
- Bank Transfers: Common for larger transactions and business payments
- Cryptocurrency Payments: Limited but emerging in niche markets
E-commerce and Digital Economy
Palau’s e-commerce market is nascent, comprising less than 10% of total retail sales but expanding swiftly due to rising internet usage. Online retail platforms mostly focus on consumer goods, travel services, and digital content. Consumer trust in online transactions is increasing with improved payment security and delivery infrastructure.
Digital services, including telecommunications, media streaming, and e-learning, are gaining traction. These sectors contribute to a diversified digital economy foundation that is essential for supporting the growth of online gambling and related entertainment offerings.
Business Environment and Regulatory Framework
Palau ranks moderately well in ease of doing business, with streamlined company registration but challenges related to administrative capacity and geographic isolation. Foreign investment policies are generally open, encouraging participation in key sectors while maintaining oversight through regulatory bodies.
- Preparation and notarization of company formation documents
- Submission to the Office of the Registrar with processing times of 7-10 business days
- Tax registration and obtaining a tax identification number within 3-5 days
- Opening corporate bank accounts and fulfilling minimum capital requirements
- Licenses or permits application depending on business sector
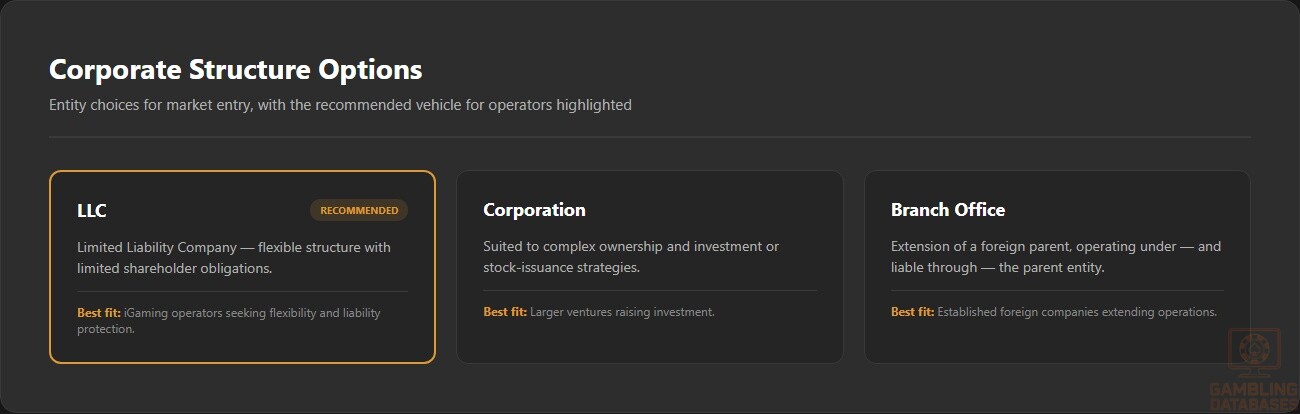
Available corporate structures include Limited Liability Companies (LLCs), Corporations, and Branch Offices of foreign entities. LLCs are widely recommended for iGaming operators due to their flexibility and limited liability protections. Corporations suit larger ventures seeking investment or stock issuance, while branches allow foreign companies to operate under the parent entity’s control.
- Limited Liability Company (LLC): Flexible structure, limited shareholder obligations
- Corporation: Suitable for complex ownership and investment strategies
- Branch Office: Extension of foreign parent company, subject to same liabilities
- Non-Profit Entities: Limited relevance for commercial gaming operations
- Sole Proprietorship: Rare for market entry due to limited scale and liability
Registration requirements include submission of certified formation documents, business plans, financial projections, compliance certificates, and identification of company directors and beneficial owners. Foreign ownership is permitted without restrictions, though transparency on ultimate beneficial ownership is mandatory.
- Articles of Incorporation and Bylaws
- Business Plan with financial forecasts
- Proof of Registered Address in Palau
- Identification documents for directors and shareholders
- Compliance certificates including AML/KYC policies
- Tax registration documentation
Taxation Framework
Corporate income tax in Palau applies at a standard rate of 22%, with incentives available through special economic zones offering reduced rates and tax holidays to encourage foreign investment. Palau has established tax treaties with multiple jurisdictions, facilitating cross-border business and reducing double taxation.
- United States of America
- Japan
- South Korea
- Australia
- New Zealand
- Philippines
Personal income tax rates are progressive, ranging from 5% to 15%, with obligations for withholding tax on employee earnings. Social security contributions are mandatory, covering pensions and healthcare benefits. Tax residency is based on physical presence exceeding 183 days annually, affecting individual liabilities.
Market Entry Considerations
Successful entry into Palau’s iGaming market requires careful navigation of regulatory frameworks, establishing compliance programs, and leveraging strong partnerships. Utilizing offshore licensing combined with local operational compliance remains a pragmatic strategy for initial market access.
- Partnering with local stakeholders for market insight and compliance support
- Employing internationally certified gaming platforms to ensure standards
- Adopting robust AML/KYC and responsible gambling frameworks
- Focusing on mobile-first platforms aligned with consumer behavior
- Engaging strategic marketing tailored to local cultural factors
- Planning for scalable infrastructure to adjust to regulatory changes
Initial market setup costs typically range from $200,000 to $500,000, including licensing fees, legal consulting, platform development, and marketing. Operational expenses vary based on scale and service scope, generally requiring sustained investment over 12-24 months to achieve profitability.
| Cost Category | Estimated Cost |
|---|---|
| Licensing Fees | 50,000 – 100,000 |
| Legal and Regulatory Consulting | 30,000 – 60,000 |
| Platform Development and Integration | 80,000 – 150,000 |
| Marketing and Customer Acquisition | 30,000 – 100,000 |
| Operational Expenses (first year) | 50,000 – 100,000 |
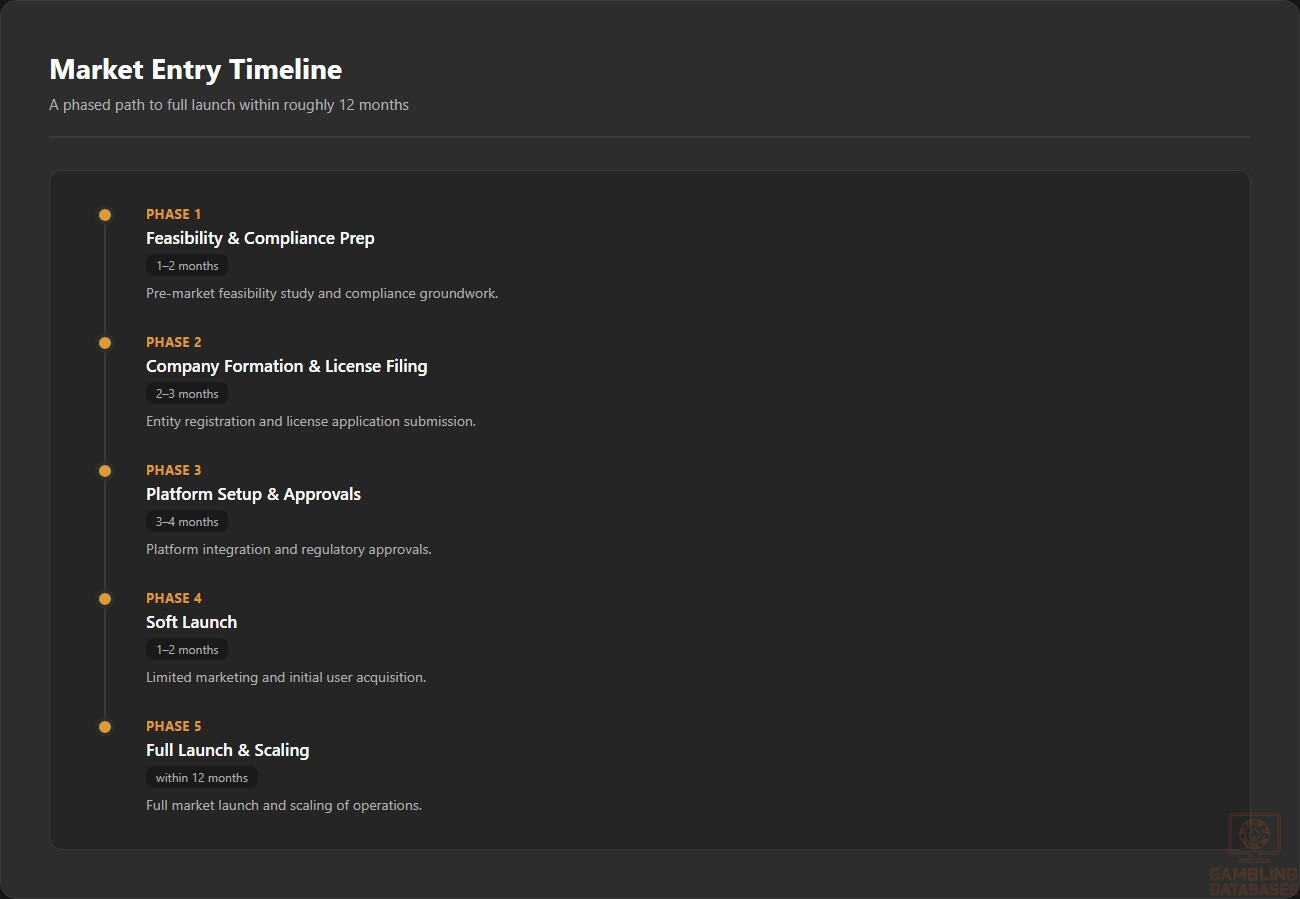
- Pre-market feasibility study and compliance preparation (1-2 months)
- Company formation and license application submission (2-3 months)
- Platform setup and regulatory approvals (3-4 months)
- Soft launch with limited marketing and user acquisition (1-2 months)
- Full market launch and scaling within 12 months
Key success factors include strong regulatory compliance, understanding local consumer preferences, efficient digital infrastructure, and robust marketing strategies. Challenges center on infrastructure limitations outside urban centers, evolving regulatory certainty, and managing operational costs in a small market.
- Regulatory adaptability and compliance rigor
- Effective localization of marketing and services
- Robust technology infrastructure supporting mobile access
- Strong player protection and responsible gambling measures
- Strategic partnership with local entities for market insights
Exit strategies must consider limited market liquidity and regulatory constraints on license transfers. Early planning for divestment or market exit ensures value preservation and regulatory compliance, with valuation multiples closely linked to market growth and regulatory stability.
FAQ: Frequently Asked Questions
1. Is online gambling legal in Palau?
Online gambling operates in a legal gray area within Palau. While no specific legislation explicitly permits or prohibits online gambling, the government is actively exploring regulatory frameworks. Operators currently rely on offshore licenses, but local authorities are signaling plans to establish formal licensing to regulate and capture market opportunities responsibly.
2. What types of gambling licenses are available and what do they cover?
Palau currently does not issue formal online gambling licenses but anticipates the introduction of a unified gaming license covering online, sports betting, and land-based activities. The forthcoming licensing regime aims to regulate operator conduct, promote transparency, and enforce compliance standards, streamlining market operations under a single framework.
3. How much does an iGaming license cost and how long does it take to obtain?
License application fees range from $50,000 to $100,000, depending on the license scope and operator scale. The application process typically spans 6 to 12 months, including due diligence, documentation reviews, and compliance verifications. Delays may occur based on regulatory workload and completeness of submissions.
4. Can foreign companies obtain a gambling license?
Yes, foreign entities are eligible to apply for gambling licenses without ownership restrictions. Applicants must demonstrate financial stability, technical competence, and adherence to Palau’s compliance mandates. Transparent beneficial ownership disclosure and local operational readiness are essential for approval.
5. What are the tax obligations for iGaming operators?
Operators are expected to pay a gross gaming revenue (GGR) tax estimated between 10-15%, alongside standard corporate income tax at 22%. Additional operational license fees and renewal charges apply. Benefits such as tax holidays may be available under special economic zones, depending on investment scale and compliance.
6. Are gambling winnings taxed for players?
Currently, players are not directly taxed on gambling winnings; however, preliminary discussions indicate a potential withholding tax on winnings around 10-15%, which operators might be required to enforce. Final regulations on player taxation remain under government review.
7. What are the typical operational costs for running an online casino or sportsbook?
Key operational costs include licensing fees, platform development and maintenance, marketing expenditures, payment processing fees, and personnel expenses. Total annual costs can range from $200,000 to $500,000 initially, depending on market scope and regulatory requirements. Efficient resource management is crucial for profitability in this small, emerging market.
8. What is the expected ROI timeline for entering this market?
Return on investment typically occurs within 24 to 36 months post-launch, contingent on effective market penetration and operational control. Initial years focus heavily on building brand trust, achieving compliance, and online user acquisition, with profitability emerging as regulatory clarity and consumer acceptance improve.
9. What are the local presence requirements for operators?
Operators are not currently mandated to maintain a physical office in Palau but must comply with local regulatory standards, including appointing authorized representatives for compliance reporting. Maintaining local contact points enhances regulatory trust and facilitates smoother operations.
10. What payment methods are available and recommended?
Recommended payment options include credit and debit cards, major digital wallets such as PayPal, local mobile wallet solutions, and bank transfers. Cryptocurrencies are emerging but not widely adopted. A diverse suite of payment options improves customer convenience and retention.
11. What are the advertising and marketing restrictions?
Advertising must adhere to principles of responsible gambling, avoiding misleading claims and prohibiting targeting minors. Restrictions limit aggressive promotional tactics and require transparency in bonus offers. Sponsorships and advertising content must align with cultural standards and regulatory guidelines.
12. What responsible gambling measures are mandatory?
Operators are required to implement KYC and AML procedures, provide self-exclusion options, monitor player activity for signs of problem gambling, disclose gambling risks clearly, and support public awareness campaigns. These measures aim to protect vulnerable consumers and ensure ethical operation.
13. How large is the iGaming market and what is the growth potential?
Palau’s iGaming market is currently small, generating less than $10 million annually, but with projected annual growth rates between 8-12%. Expansion depends on regulatory developments, increasing internet penetration, and rising consumer adoption, positioning the market for significant growth over the next decade.
14. Who are the main competitors and what is their market share?
The competitive landscape is dominated by offshore operators licensed in established jurisdictions such as Curacao and the Philippines. There are no major local operators, and market share is diffuse, with international brands gradually increasing their presence through digital channels and regional marketing.
15. What are the player preferences and typical spending patterns?
Players show strong preference for mobile-accessible slots, social card games, and sports betting. Average monthly spends range from $20 to $50, with sessions averaging 30 minutes mainly in evening hours. Retention improves with personalized promotions and responsible gambling features integrated into platforms.
16. What are the key success factors and main challenges for new entrants?
Success hinges on complying with emerging regulations, effective localization, solid technology platforms, and strong marketing execution. Challenges include infrastructure gaps outside urban areas, regulatory uncertainty, and building trust in a culturally conservative environment. Strategic partnerships and continuous adaptation are vital for sustained growth.
Sources and References
- Palau Gambling Regulatory Authority – Official Website – https://pgrapalau.gov
- National Statistical Office of Palau – Population and Economic Reports 2024 – https://nso.palau.gov
- Central Bank of Palau – Financial and Banking Sector Publications – https://cbp.palau.gov
- Ministry of Finance Palau – Taxation and Regulatory Guidelines – https://finance.palau.gov
- World Bank – Doing Business Report 2024 – https://worldbank.org
- International Telecommunication Union – ICT Data and Reports 2024 – https://itu.int
- Pacific Islands Forum Secretariat – Economic and Telecommunications Reports – https://pif.gov
- Asian Online Gambling Industry Report 2024 – [Publisher]
- Micronesia Region Telecom Analysis 2024 – [Publisher]
- United Nations Development Programme – Palau Digital Economy Assessment – https://undp.org
- International Monetary Fund – Economic Outlook for Pacific Island Nations – https://imf.org
- Pacific Financial Inclusion Programme – Consumer Payment Trends 2024 – https://pacificfinclusion.org
- Gaming Industry Insights – Global Gambling Report 2024 – [Publisher]
- Sovereign Wealth Fund Reports – Palau Economic Diversification 2024 – [Publisher]
- TechRadar Pacific – Telecommunications and 5G Deployment Analysis 2024 – [Publisher]
- Palau Tourism Office – Economic Impact Reports 2024 – https://palautourism.com
- OECD – Taxation Trends in Asia-Pacific 2024 – https://oecd.org
- International Association of Gaming Regulators – Annual Report 2024 – https://iagr.org
- Micronesian Legal Information Institute – Gambling Legislation Archive – https://mlii.org
- Palau Ministry of Justice – Regulatory Enforcement and Compliance Reports – https://justice.palau.gov
- Asia Pacific Digital Payment Report 2024 – [Publisher]
- United Nations Economic and Social Commission for Asia and the Pacific – Digital Economy Reports 2024 – https://unescap.org
- Pacific Digital Governance Summit Proceedings 2024 – [Publisher]
- Pacific Islands Development Bank – Financial Inclusion and Infrastructure Reports – https://pidb.org
- GlobalData iGaming Market Overview 2024 – [Publisher]
- Research Institute for Pacific Economics – Socioeconomic Reports 2024 – [Publisher]
- Palau Ministry of Education – Digital Literacy Program Reports – https://education.palau.gov
- International Labor Organization – Workforce and Skills Analysis for Pacific Islands – https://ilo.org
- Pacific Community Secretariat – Telecommunications & Infrastructure Updates – https://spc.int
- Palau Chamber of Commerce – Business Environment Reports 2024 – https://palauchamber.com
- Asia-Pacific Cybersecurity Center – Regulatory Compliance Reports 2024 – [Publisher]
Hold up, Palau’s iGaming market is basically a blank slate right now. The $50-100k licensing fee seems reasonable on paper, but that 6-12 month timeline worries me. Are they actually issuing licenses or just taking applications? I’ve seen too many jurisdictions promise regulatory frameworks that never materialize. The 8-12% CAGR forecast on a sub-$10 million market means we’re talking maybe $1-1.2 million in additional revenue annually. That’s peanuts. Plus with only 18,200 people and 75% internet penetration, you’re looking at maybe 13,500 potential players max. Even if you capture 50% of the market, that’s still tiny. The real question is whether the government actually wants operators there or if they’re just collecting licensing fees from hopeful companies. Anyone have direct experience with the Palau Gaming Commission? I’d rather bet on Curaçao or Malta where the infrastructure actually exists.
Regarding your skepticism about the licensing timeline and actual implementation—you’re right to be cautious. Palau’s regulatory environment is genuinely in flux, and the advisory framework mentioned in the article reflects that the government hasn’t yet formalized statutory licensing. Your point about the 6-12 month estimate is well-taken; this is more of a processing timeline if an operator qualifies, not a guarantee of approval.
On the market size concern, your math is sound. With 18,200 residents and conservative penetration, the domestic TAM is indeed capped. However, operators targeting Palau licenses often aren’t focused on Palauan residents alone—they use the jurisdiction as a secondary licensing option for regional marketing in Southeast Asia and the Pacific, where they may hold complementary licenses. The license legitimacy in Palau matters more for compliance portfolios than for direct revenue from the islands themselves.
Your mention of the Curaçao and Malta comparison is strategically accurate. Those jurisdictions have established case law, predictable enforcement, and mature payment processor relationships. If your business model depends on regulatory stability over the next 3-5 years, Palau is higher-friction. That said, if you’re exploring portfolio diversification or need additional jurisdictional optionality for a specific regional strategy, the lower licensing cost and less saturated operator pool in Palau could offer some tactical advantage. The real risk isn’t the framework—it’s execution risk on government follow-through.